Pénzügyek
50/30/20 rule: how to put together your family budget
How much should go towards essentials, discretionary spending and savings? We explain the 50/30/20 rule and how to apply it flexibly, using examples based on median net earnings.
2026-11-19 · 5 min read
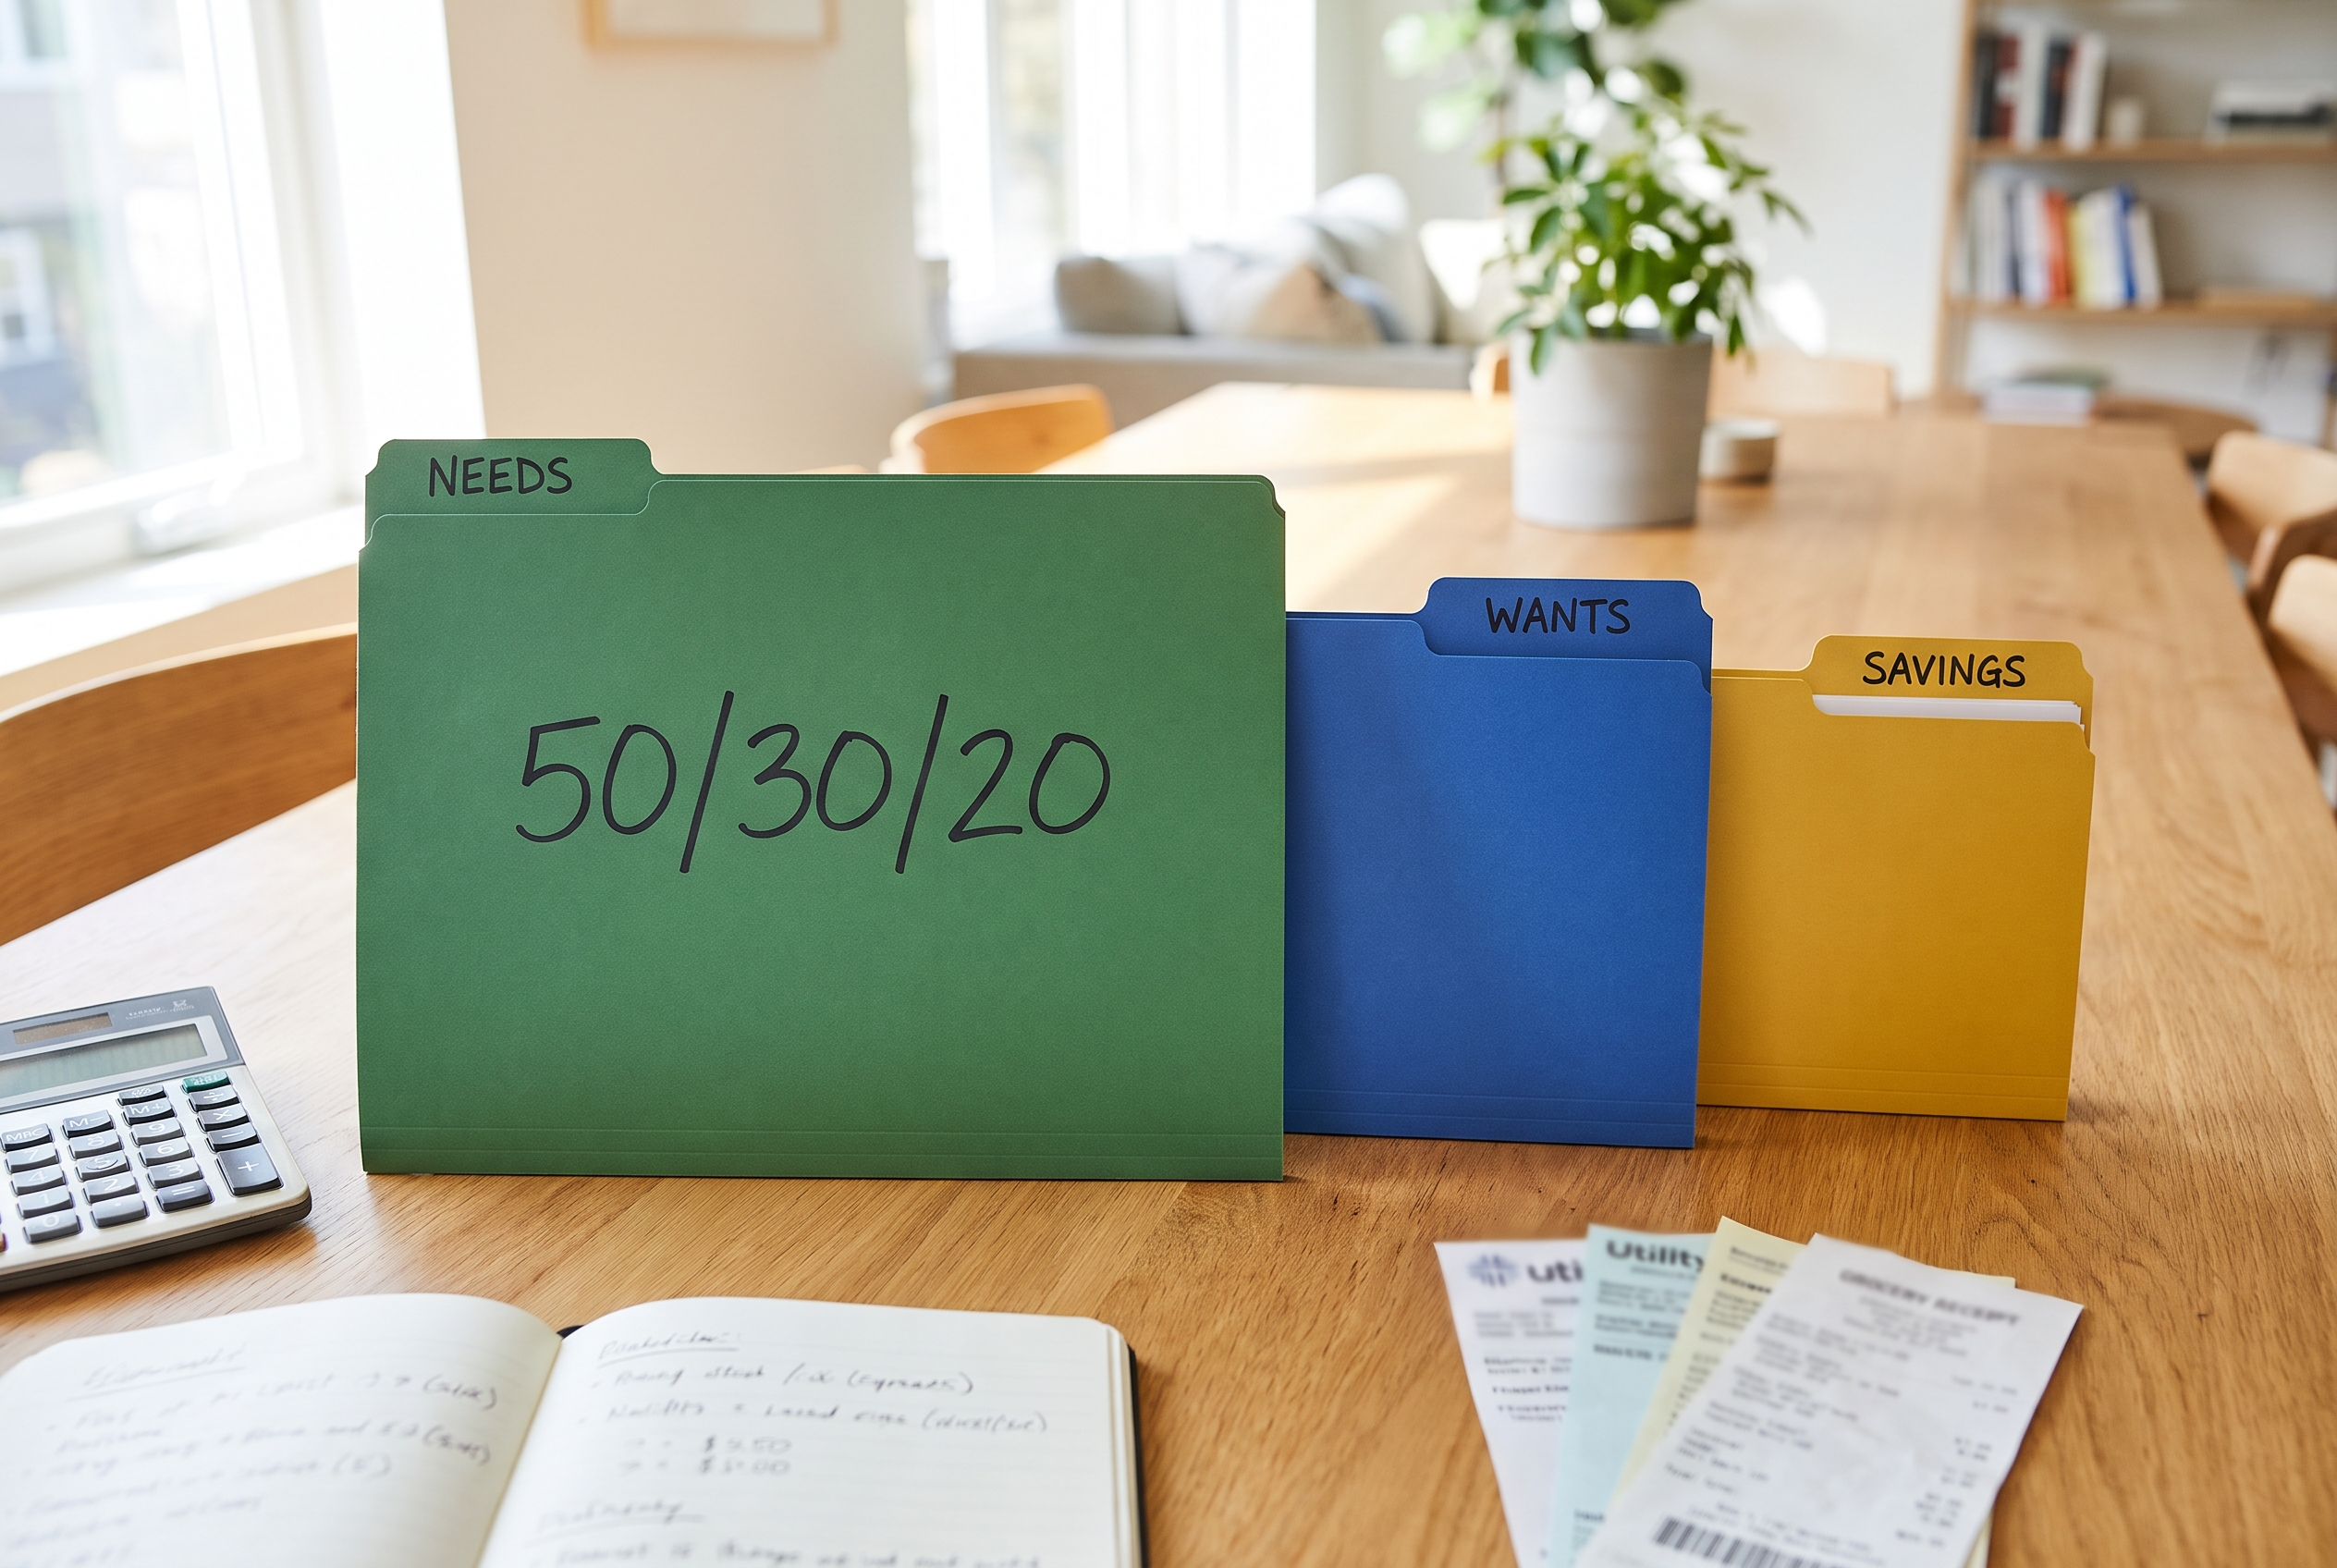
After paying for housing, bills and food, how much should be left for leisure, and how much should you set aside? The 50/30/20 rule gives each of these a separate place in the family budget: according to Kriszta Papszt's financial guide, it allocates half of net income to needs, 30 per cent to wants, and 20 per cent to savings and debt reduction. The question is how to adapt this to your own income and expenses.
Start with your own net income, not average gross earnings
Your budget should be based on the money you actually have available. When planning a family budget, list the regular net income available for shared expenses and record occasional income separately. This prevents a one-off bonus from quietly becoming a permanent source of funding for everyday spending.
Median net earnings can be a useful reference point for understanding earnings in Hungary. According to the Hungarian Central Statistical Office's September 2026 earnings release, median net earnings were HUF 435,600, while average gross earnings for full-time employees were HUF 737,400. The two figures are not interchangeable: gross and net amounts differ, and the mean and median are also different measures.
The median marks the middle of the earnings distribution: as many people earn less as earn more. However, it does not represent a family's disposable income or tell you how much you should be able to live on. Use your actual income in your own plan; the national figure is only the starting point for the numerical example here.
Organise spending into three categories
In Kriszta Papszt's guide, the 50/30/20 split separates basic living costs, wants and money set aside for the future. You could try the following categories in your own records:
- Needs: housing, basic groceries, utility bills and the transport you need to get to work.
- Wants: eating out, entertainment, optional subscriptions and purchases you can postpone.
- Savings and debt reduction: an emergency fund, money set aside for future goals, and debt repayments above the required minimum.
When categorising spending, consider its purpose as well as where you bought something. A basic ingredient and a more expensive treat for a special occasion may appear on the same supermarket receipt but serve different purposes in your budget. You do not need to analyse every small item separately: choose a level of detail you can maintain.
How the split works with net earnings of HUF 435,600
Applying the proportions in the guide to the median net earnings reported by the Hungarian Central Statistical Office gives the amounts below. These are our own calculations, not estimates of living costs, and they do not mean that the resulting budgets would be sufficient for every household.
- Needs: 435,600 × 0.50 = HUF 217,800.
- Wants: 435,600 × 0.30 = HUF 130,680.
- Savings and debt reduction: 435,600 × 0.20 = HUF 87,120.
If a household had two earners each receiving this net amount, their combined income would be HUF 871,200. Using the same calculation, HUF 435,600 would go towards needs, HUF 261,360 towards wants, and HUF 174,240 towards savings and debt reduction. This is an illustrative example, not a description of a typical Hungarian family's income or expenses.
Review your actual spending before setting targets
Start with a bank statement for a completed month and add any cash purchases. Assign the items to your chosen categories, then compare the totals with your planned budgets. This means you do not have to rely on memory to identify where you might have room to adjust.
You can also list predictable expenses that do not occur every month, such as an annual fee or planned back-to-school shopping. You can set aside a monthly amount for these within the category that matches their purpose. Setting money aside in advance for a known bill does not mean you should also count it as long-term savings.
Next, choose one clearly defined change. For example, you could check whether you use all your subscriptions or decide which optional purchases you would be happy to postpone for a more important goal. Make the plan specific, but do not assume that every expense can be freely reduced.
Do not count your mortgage twice
When recording loan repayments, it is easy to confuse a required monthly expense with voluntary debt reduction. One option for your spreadsheet is to include the required mortgage payment under housing and any additional payments under savings and debt reduction. This is a suggestion for keeping records, not a requirement relating to your loan agreement.
The key is to record each amount only once. If you are considering an early repayment, check the terms of your own agreement and any possible charges first. The budgeting ratio alone does not determine which financial step is more favourable in your circumstances.
Give your emergency fund a separate target
Kriszta Papszt's guide recommends building an emergency fund covering at least three months as the first goal for the savings allocation. Treat this as a starting recommendation, not a mandatory amount that applies to everyone. You can adapt your own target to the essential expenses you would need to cover during a loss of income or an unexpected situation.
In your records, you can separate your emergency fund from money saved for a holiday or another planned purchase. If you draw on it, the guide prioritises replenishing it; you can choose a realistic pace for doing so in your own plan. This keeps the purpose of each pot of money clear.
If essential costs exceed the allocation, adjust the plan
If housing and other necessary expenses do not fit within half your income, that does not mean you are managing your household badly. Use the ratio as a reference point, not as an expectation that leads you to hide expenses on paper. First, identify which costs you can change at all and which are fixed in your current circumstances.
You do not have to spend the full wants allocation simply because the formula assigns that much to it. If money is left over, you can redirect it towards a chosen goal; if the planned savings amount is too ambitious, you can look for a smaller, sustainable amount. When discussing the budget as a family, it is also worth considering which compromises each person is comfortable making for shared goals.
A workable budget stays manageable
Use the 50/30/20 rule as a starting plan that you can adapt to your own income and commitments. Review your actual spending regularly, avoid double-counting and give the money you set aside a clear purpose. This article provides general financial information, not personalised financial advice; before making a decision about borrowing or investing, consider consulting an appropriate professional.
Sources used
- 1.KSH Keresetek gyorstájékoztatóksh.huverified
- 2.Mi az az 50/30/20-as költségvetési szabály?papsztkriszta.comverified
- 3.KSH Módszertan - Kereseti mutatókksh.hu
- 4.Váratlan nyugdíjkorhatár-csökkentés jöhetpenzcentrum.hu
- 5.Nyugdíjak és inflációs várakozások 2027allampapirkalkulator.hu
These sources were used during our editorial fact check.